

Turn Data into Decision Power.
AI & Big Data Solutions
Unlock the hidden potential of your enterprise data. SFIN delivers AI models and deep big data analytics for credit scoring, real-time fraud detection and cash flow optimization.
Every day, financial and retail businesses generate millions of records: transactions, orders, payment histories, app usage. Most of that data just sits in a database. SFIN’s AI & Big Data solutions turn data into decisions: approve credit in seconds, stop fraudulent transactions before money leaves the account, and forecast cash flow and inventory more accurately.
SFIN does not sell “generic AI”. We build models tied to specific business problems, with measurable impact, that run at a scale of tens of millions of transactions per day.
Why have AI and big data become essential for financial businesses?
- New customers lack credit history: tens of millions of adults in Vietnam have never borrowed formally. Traditional scoring ignores them, yet they are a large untapped market.
- Fraud is getting more sophisticated: card fraud, transfer scams and identity theft happen in seconds. Manual checks and static rules cannot keep up.
- Decisions must be fast: customers buying on installments or applying for consumer loans expect approval at the counter or in the app, not days later.
- Fragmented data: data lives in many systems, reports are slow, and every department has a different number.
SFIN’s AI & Big Data solutions
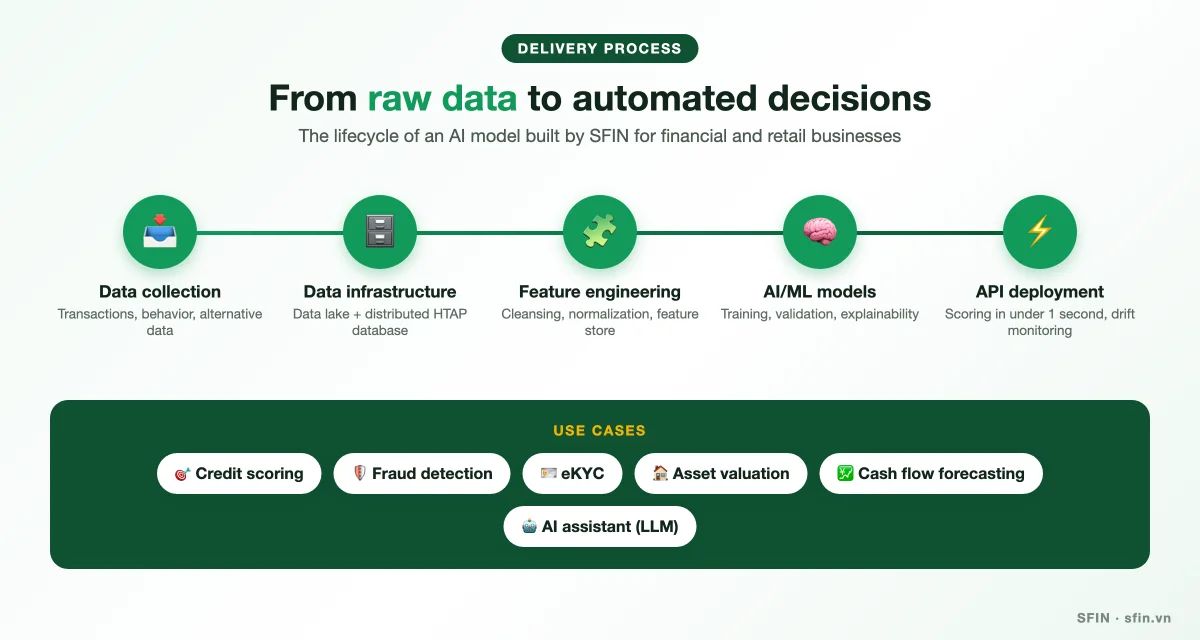
1. Credit scoring with alternative data
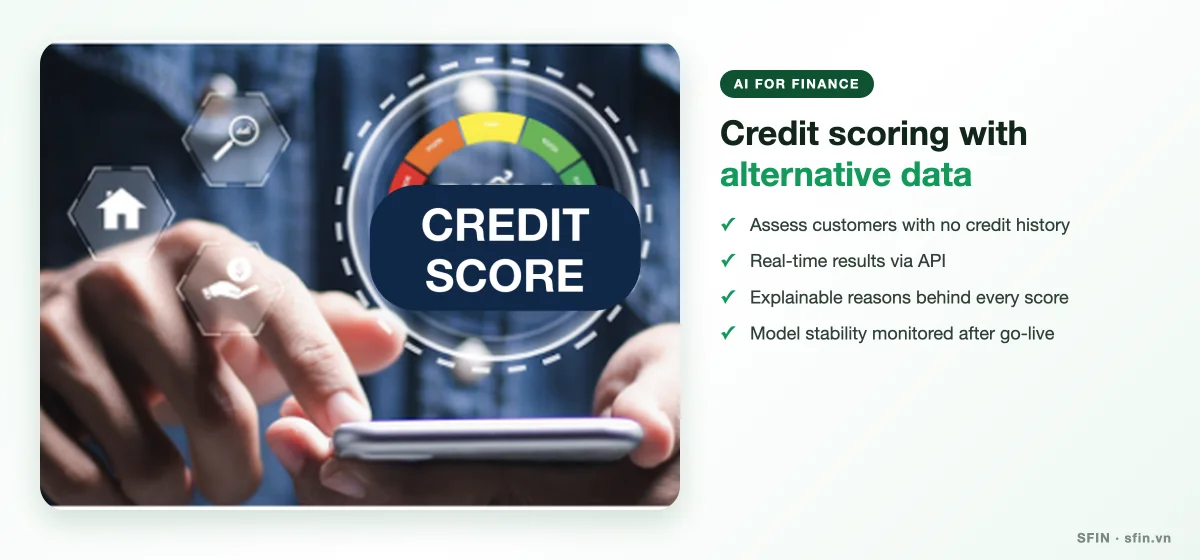
Beyond traditional credit data, SFIN’s models use alternative data that customers consent to share: transaction history, sales revenue, bill payment behavior and cash flow stability. The results:
- Customers with no borrowing history, such as household businesses and young professionals, can be assessed.
- Scores and risk grades are returned via API in real time, supporting automated loan approval or point-of-sale installment offers.
- Explainable: every score comes with its main contributing factors, so credit officers understand and stay in control of each decision.
For household businesses using SOFIN sales software, revenue standardized through e-invoices becomes reliable evidence that helps lenders make faster financing decisions.
2. Real-time fraud and anomaly detection
The system combines business rules with machine learning models to score the risk of every transaction as it happens: unusual frequency, unfamiliar locations, amounts outside normal patterns, new devices, and transaction chains that suggest money laundering. High-risk transactions are flagged or held for verification.
SFIN has built a credit scoring and anomaly detection system for a national-scale payment infrastructure organization, processing around 35 million transactions per day.
3. Electronic identity verification (eKYC) and asset valuation
- eKYC: ID document reading with OCR, face matching and liveness checks, so customers can open accounts and sign contracts online in minutes.
- Asset valuation: models estimate the value of collateral (such as cars and motorbikes) based on market data, making secured lending faster and more consistent.
4. Forecasting and big data analytics
- Cash flow and revenue forecasting by outlet and by season.
- Demand forecasting and replenishment suggestions to reduce both overstock and stockouts.
- Customer segmentation, product recommendations and targeted promotions.
- Real-time dashboards for leadership.
5. AI assistants and large language models (LLMs) for enterprises
SFIN fine-tunes large language models on each business’s own data and processes. Managers can ask questions in plain language, such as “Which outlets saw revenue fall this week?”, and get answers backed by data instead of waiting for an analyst’s report. The AI assistant is already built into the SOFIN Pro retail chain management platform.
Data infrastructure built for scale
An AI model is only as good as its input data: complete, clean and timely. SFIN designs data infrastructure around these principles:
- Separate transactional and analytical workloads: sales and payment systems never slow down when heavy reports run.
- Distributed HTAP database: SFIN has a strategic partnership with PingCAP to deploy TiDB, a database that handles transactions and analytics on the same data and scales horizontally as volumes grow.
- Shared feature store: data features are standardized once and reused across models.
- Post-deployment model monitoring: tracking data drift and model performance, with scheduled retraining.
Responsible data and AI governance
Financial data is sensitive. Every SFIN solution follows these principles:
- Data subject consent and purpose limitation, in line with Decree No. 13/2023/ND-CP and Vietnam’s Personal Data Protection Law.
- Encryption and anonymization of data used for model training; role-based access control.
- Humans make the final call on important cases; AI supports and alerts.
- Bias testing so models do not discriminate against any customer group.
Track record
- National-scale payment infrastructure organization: credit scoring and anomaly detection system, around 35 million transactions per day.
- A digital data partner: big data analytics and data-driven credit scoring.
- A foreign-invested agribusiness: dealer management platform collecting sales data from its distribution network.
- FINBLUE: AI models that approve buy now, pay later (BNPL) limits and P2P loans.
- SOFIN Pro: real-time reporting, BI and an AI assistant for Vietnam’s largest retail chain, with more than 11,000 outlets.
How we work together
- Define the problem and success metrics: for example, lower bad debt, higher approval rates or reduced fraud losses.
- Assess the data: review data sources, quality and gaps to fill.
- Build a prototype model: train on historical data and compare with the current approach.
- Run side by side (champion–challenger): the new model runs alongside the existing process to measure real-world impact.
- Deploy and monitor: go live via API, with ongoing monitoring and scheduled retraining.
Frequently Asked Questions
How much data does a business need to start using AI?
It depends on the use case. Credit scoring typically needs historical data on tens of thousands of applications with known repayment outcomes. Revenue forecasting works well with 12 months or more of sales data. SFIN assesses your data before making a proposal.
Can SFIN’s credit scoring models explain their results?
Yes. Every score comes with its main contributing factors, so credit officers and regulators can see why an application was approved or declined.
Will our data leave our environment?
No. The solution can be deployed on your own infrastructure or a private cloud, with data encrypted and used only for the agreed purposes.
Will AI replace credit officers?
No. AI quickly handles clear-cut applications and flags risky ones, so officers can focus on cases that need expert judgment.
Contact us
Start with a conversation about your business problem and your existing data with SFIN’s AI experts.
- Hotline: (+84) 969 877 888
- Email: [email protected]
- Contact page: sfin.vn/contact
Read more: Digital Payment & Fintech Solutions · AI in Finance: 5 Ways AI Is Reshaping the Fintech Stack · SFIN & PingCap: Deploying TiDB for Big Data in Fintech
AI & Big Data Solutions
Need advice?
Hotline: (+84) 969 877 888
Email: [email protected]
Request for quote now!
Discuss your challenges and opportunities
Whether you’re exploring a challenge or ready for a full diagnosis — we’re here to listen. No bots — just a real expert ready to talk.